Wind insurance is the single biggest line item in a Florida Keys homebuying budget, and in 2026 it is finally coming down, but only slightly. Monroe County still has the highest average homeowners premium in Florida at about $7,863 a year for a policy that includes wind, and roughly $6,000 of that is the wind component alone. For a typical Keys buyer, wind coverage adds hundreds of dollars a month to a mortgage payment before you factor in a single payment of principal and interest.
This guide answers the question buyers ask me most: how much does wind insurance actually cost in the Florida Keys in 2026? I will walk through the real numbers by property type, what the 2026 rate relief did and did not change, how wind costs affect your mortgage qualification, and what you should budget before you make an offer.
What Wind Insurance Costs in the Florida Keys in 2026
Wind insurance in the Keys is typically a wind-only policy, separate from your standard hazard policy, because most private carriers exclude wind damage from standard homeowners coverage in Monroe County. That means two policies, and the wind-only piece is the expensive one.
Based on the most recent Florida Office of Insurance Regulation market data (the July 1, 2026 report, using numbers as of March 31, 2026), here is where Monroe County stands:
- Average annual homeowners premium including wind: about $7,863, the highest of any county in Florida.
- Average annual premium excluding wind: about $1,871, which is the hazard, fire, theft, and liability portion.
- The wind component: roughly $6,000 a year on average, once you subtract the non-wind coverage.
Those are county averages, and real properties sit on both sides of them. For typical single-family homes in the Keys, wind-only premiums in 2026 run about $4,000 to $12,000 a year. Newer elevated construction with impact windows, a modern roof, and documented wind mitigation often lands in the $3,500 to $7,000 range. Older homes and waterfront properties are the most expensive, frequently $12,000 to $22,000 a year. If you are financing a home in Key Largo, Islamorada, Marathon, or Key West, budget around the county average first, then refine it with a real quote for the specific property.
What Wind Costs Look Like by Property Type
Wind insurance pricing in the Keys is driven by the property's replacement cost, construction, age, and how it is elevated. Here is the practical range for the main property types buyers ask about:
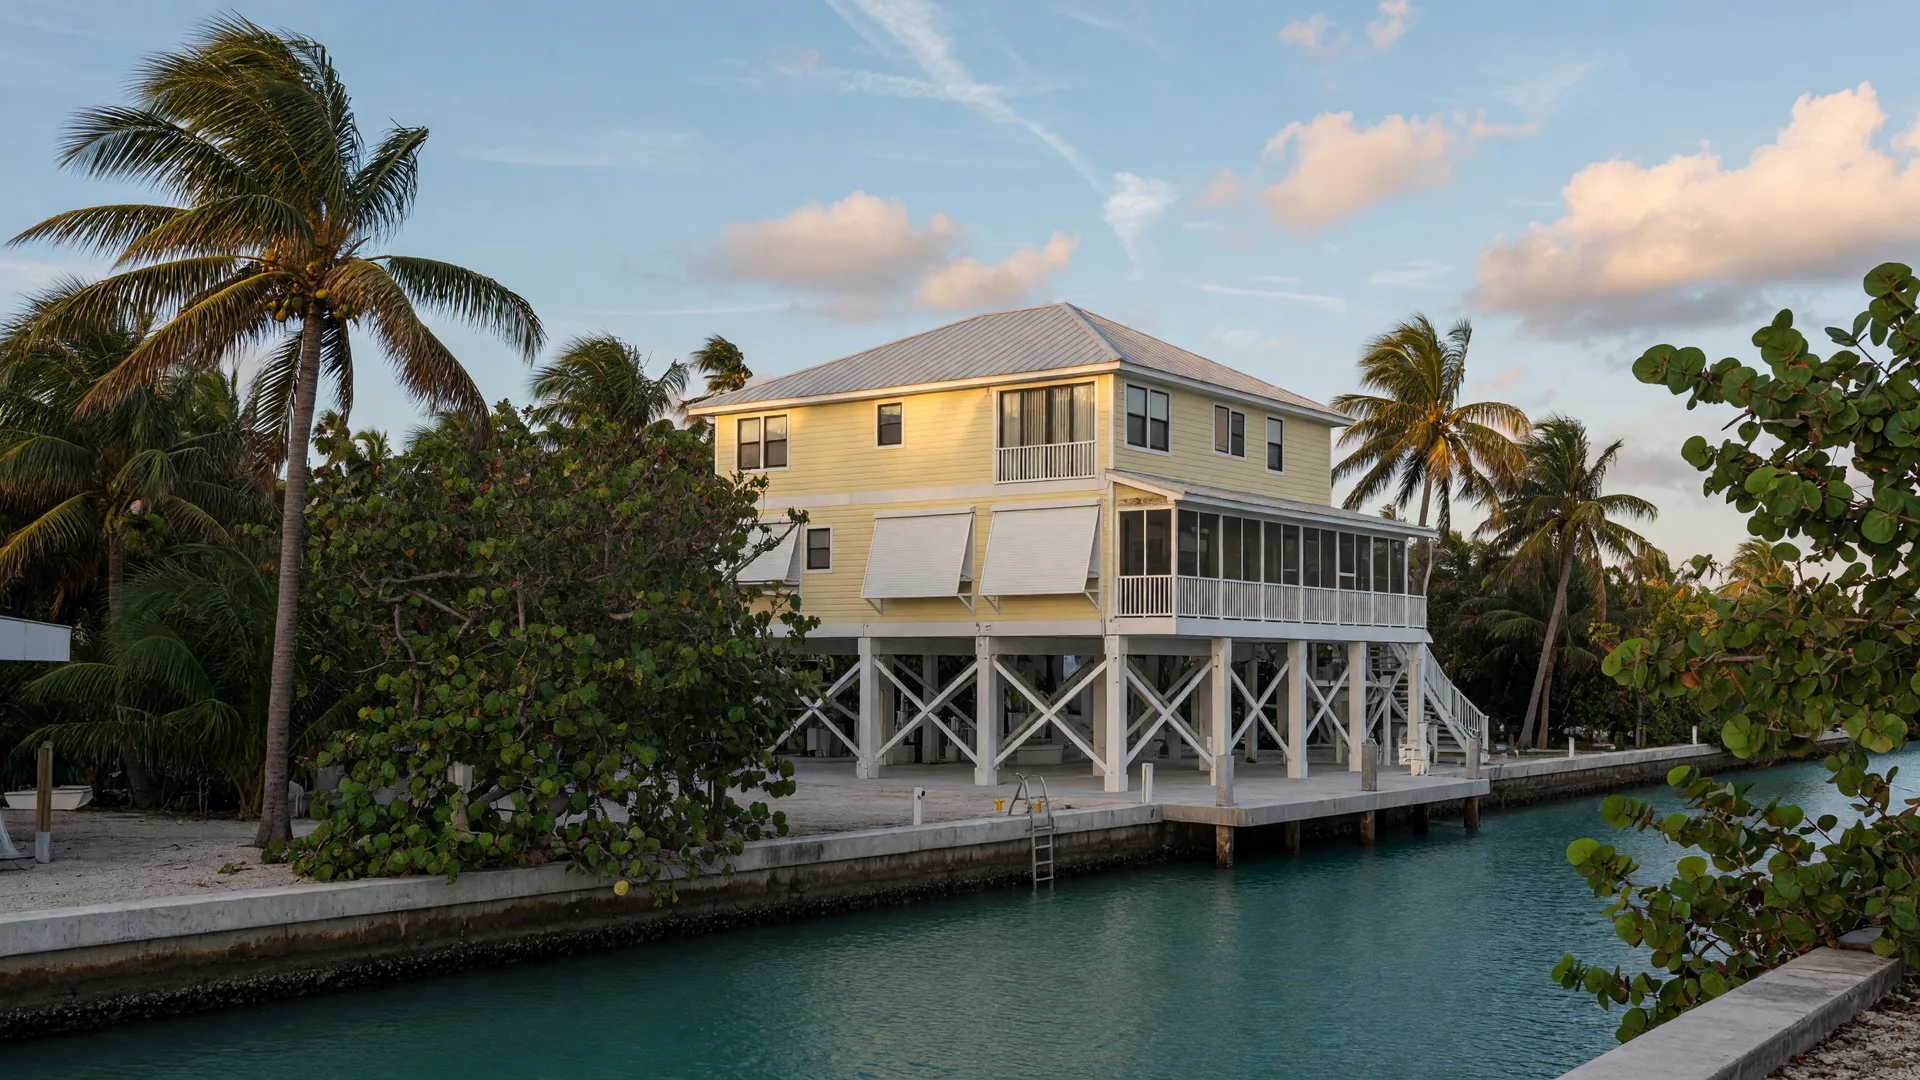
- Newer single-family homes built to current code: $3,500 to $7,000 a year. These homes are elevated, have impact-rated windows and doors, and carry current wind mitigation inspections, which earns the largest credits.
- Typical older single-family homes: $7,000 to $12,000 a year, the most common range in the Keys.
- Waterfront and older frame homes: $12,000 to $22,000 a year. Replacement cost and exposure drive these up fastest.
- Condominiums: wind coverage on the building is carried by the HOA master policy, so unit owners pay for wind through monthly association dues rather than a separate wind-only policy. That is why condo wind exposure can look lower on paper, but the master policy premium is baked into your HOA fee, and a weak master policy can mean special assessments after a storm. Lenders review the master wind coverage as part of condo financing approval.
On top of wind, you will also carry standard hazard insurance and, in most cases, flood insurance. Total annual insurance for a typical Keys home often lands between $15,000 and $25,000 once all three are added together. That total, not just the wind piece, is what belongs in your affordability conversation from day one.
Why the Keys Are Still the Most Expensive County in Florida
Even with 2026 rate relief, Monroe County remains the most expensive county in Florida for wind coverage, and the gap is not small. The reasons are structural:
- Monroe County sits in the highest wind zone in the state. Florida's building code treats the Keys as the most wind-exposed region, and insurers price accordingly.
- There is very little private wind competition. Most private carriers that have returned to Florida still exclude Monroe County. Citizens Property Insurance, the state-backed insurer of last resort, effectively carries the bulk of Keys wind policies, and it is the fallback that makes financing possible at all.
- Homes are expensive to replace. High property values mean high dwelling replacement costs, and wind premiums are calculated as a percentage of that number.
- Older housing stock. A large share of Keys homes predate modern wind codes and need mitigation work to earn the best rates.
For more on how Citizens wind-only policies work and the 50 Percent Rule, see the full wind insurance guide.
The 2026 Rate Relief: What Actually Changed
After several years of steep increases, Florida insurance rates went down in 2026 for the first time in a while, and the Keys got specific relief. Here is what happened:
- Monroe County wind-only policyholders saw the largest reductions. In January 2026, the state announced that more than 1,000 Monroe County homeowners received an average 11.3 percent reduction, and more than 8,000 wind-only policies in the county saw a reduction or no increase. Monroe's annual rate-increase cap has been held near 10 percent.
- Citizens cut rates statewide. Regulators approved an average 8.8 percent decrease on Citizens homeowners multiperil policies for 2026, with wind-only policies down 5.5 percent. More than 330,000 policyholders across all 67 counties saw lower premiums, and over 150,000 received cuts of 10 percent or more.
- What is driving the relief: falling reinsurance costs at the June 2026 renewals, litigation reform, and a much smaller Citizens. Citizens has fallen from a peak of about 1.4 million policies to roughly 278,000 as private carriers take on more risk. Most of that private growth has happened outside Monroe County, which is why the Keys still lean so heavily on Citizens.
- The rate cap moved up. The statutorily required glide-path cap on Citizens rate increases rose to 15 percent on January 1, 2026, so future increases are possible even after this year's reductions.
The practical takeaway: your wind premium may be lower this year than last, but it is still the largest fixed cost of Keys homeownership, and it can still go up in future years. Budget for the current quote, and treat any year-over-year decrease as welcome relief rather than a permanent new normal.
The 2026 Hurricane Season and What It Means for Rates
The 2026 Atlantic hurricane season has been exceptionally quiet, which is relevant to the insurance picture. NOAA forecast a below-normal season under strengthening El Nino conditions, and it played out that way. The first hurricane of the season did not form until early October, the latest on record, and no storm has had a direct impact on the Keys.
Two things are worth understanding about a quiet season:
- A quiet year is not the same as low risk. Insurance pricing is driven by long-run risk models, not one quiet summer. A single season does not reset premiums, and reinsurance costs, which shape next year's rates, will move on the whole market picture, not just this year.
- Even a quiet season has real moments. The season's first hurricane made landfall in the Florida Panhandle in mid-October, and Citizens suspended new-policy binding statewide during the watch and warning window before pausing again around that landfall. That is a reminder that coverage can become temporarily unavailable at the exact moment a storm approaches, which is why you want your insurance line up and quoted before you get deep into a contract.
For the latest on where Keys mortgage rates and the housing market sit this month, see the October 2026 market update.
How Wind Insurance Affects Your Mortgage
Wind coverage is required for every mortgage in the Florida Keys, no matter the loan program. Lenders will not close a loan on a coastal property without proof of wind insurance in force from day one, and the premium is usually escrowed, meaning it is collected with your monthly payment.
Here is what that means for qualification:
- Wind insurance counts against your debt-to-income ratio. A $6,000 annual wind premium adds about $500 a month to your housing payment before principal, interest, taxes, or flood insurance. At today's rates, that is roughly $60,000 to $70,000 of buying power on a typical Keys purchase.
- Get a real premium before you build a budget. The listing price is only the start. Two otherwise similar Keys homes can have very different wind quotes based on age, elevation, roof, and mitigation features, and that difference changes what you qualify for.
- It affects every loan program the same way, from conventional and FHA loans to jumbo loans for higher-value waterfront homes, which often carry stricter coverage requirements.
- For investment properties, wind is part of the rental math. On a DSCR loan, the wind premium is a direct expense in the Debt Service Coverage Ratio calculation, so a high premium means more rental income is needed to make the numbers work.
The mitigation work that lowers your wind premium is one of the few things that improves both your insurance cost and your buying power at the same time. A documented wind mitigation inspection typically cuts wind premiums by 20 to 40 percent, which can be thousands of dollars a year in the Keys. For the full breakdown of the inspection, the revised OIR-B1-1802 form, and My Safe Florida Home grants, see the wind mitigation credits guide.
One More Cost to Watch: Flood Coverage on Citizens Policies
There is a change coming that directly affects your total insurance budget: a flood insurance requirement is phasing into every Citizens wind policy, with the target of full coverage by January 1, 2027. If you are buying a Keys home with a Citizens wind-only policy, plan on a flood premium being part of your picture, either through NFIP or a private flood policy.
Flood insurance in the Keys is already a major cost on top of wind, so this matters for your affordability math. See the flood insurance guide and the comparison of private flood vs. NFIP for what that coverage runs, and the homeowners insurance guide in the Learning Center for how all the pieces fit together.
How to Get an Accurate Wind Quote Before You Make an Offer
You should not guess at wind insurance. Here is the process I recommend to every Keys buyer:
- Ask the seller for the current wind-only premium and policy. It is usually in the seller's disclosure or available through your agent. That number is your starting point.
- Ask for the wind mitigation inspection report. If the seller has one on file, it tells you what credits are already applied. If there is no report, budget $100 to $250 for an inspection during your due diligence period.
- Get a quote from Citizens and a licensed independent agent. In Monroe County, Citizens is usually the quote that matters, but a good agent can tell you whether any private wind options exist for your specific property.
- Factor in flood and hazard. Your true insurance number is wind plus hazard plus flood, and you want all three quoted before you finalize an offer.
- Bring the total to your lender before you commit. When I run pre-approval for Keys buyers, I model the real premium into the payment so the number you are approved for reflects reality. If you have not done this yet, that is the right next step.
Frequently Asked Questions
How much is wind insurance in the Florida Keys in 2026?
Why is wind insurance so expensive in the Florida Keys?
Did wind insurance rates go down in Florida in 2026?
Is wind insurance required for a mortgage in Florida?
How can I lower my wind insurance premium in the Florida Keys?
Ready to Run the Real Numbers?
Wind insurance should not be a surprise at the closing table, and it should not quietly shrink the home you qualify for. I work with Keys buyers every day to model the true cost of ownership, including wind, flood, and hazard coverage, before they make an offer. If you are considering a home anywhere in the Florida Keys, let us run your real numbers together, including the actual premium for the property you are looking at.
Written by Austin Edwards, NMLS #2639747, Ocean Blue Lending
Published October 14, 2026
Wind Insurance Guide · Wind Mitigation Credits · Flood Insurance Guide · Blog · Learning Center