
Wind insurance is one of the largest recurring costs of owning a home in the Florida Keys, and it is one of the most misunderstood. If you are shopping for a home in the Keys, you need to understand how wind coverage works, what it costs, and what you can do to lower your premium before you make an offer.
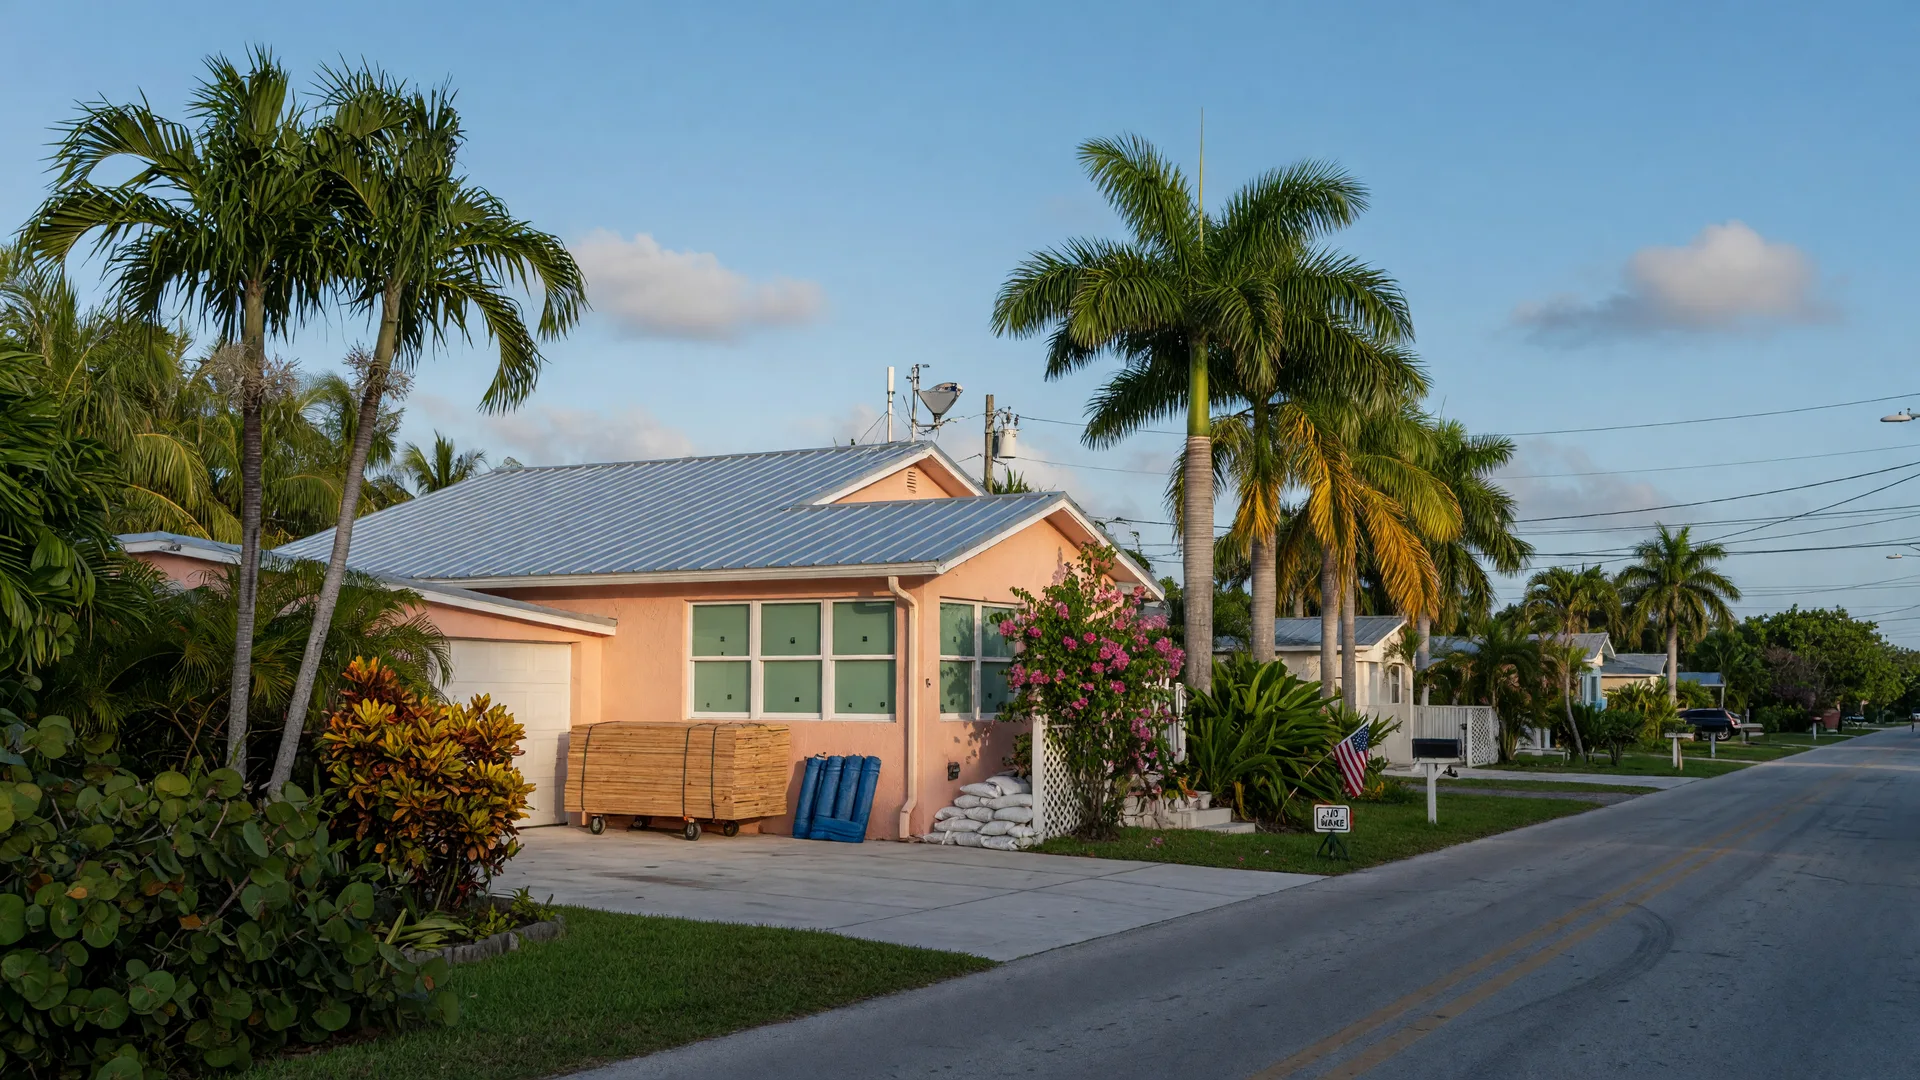
This guide covers everything Keys buyers and homeowners should know about wind insurance in 2026: how it is structured, what Citizens Property Insurance offers, the wind mitigation credits that can save you thousands, and how wind insurance fits into your total mortgage payment.
Is Wind Insurance Required in the Florida Keys?
Florida law does not require windstorm insurance by itself. But practically every mortgage lender requires it as a condition of financing for coastal properties, which makes it effectively mandatory for most homeowners in Monroe County.
Here is how it typically works: a standard Florida homeowners insurance policy usually includes wind coverage. But in high-risk coastal areas like the Keys, many private insurers exclude wind damage from standard policies. This means you need a separate wind-only policy alongside your standard hazard insurance policy.
The result is two policies where one would cover both on the mainland: a standard homeowner policy for fire, theft, and liability, and a separate wind-only policy for hurricane and windstorm damage. Both are required for most Keys mortgages.
How Citizens Property Insurance Wind-Only Policies Work
Citizens Property Insurance Corporation is Florida's state-backed insurer of last resort. It was formed from the merger of the Florida Windstorm Underwriting Association and the Residential Property and Casualty Joint Underwriting Association, and it now serves property owners across the state who cannot find coverage in the private market.
In the Florida Keys, many homeowners carry a wind-only policy through Citizens while maintaining their standard homeowner coverage through a private carrier. This split-policy arrangement is common because many private insurers in Monroe County offer policies that cover everything except wind.
Key facts about Citizens wind-only policies in 2026:
- Citizens is required by law to accept eligible applicants who cannot find private coverage
- Wind-only policy rates are capped by state law and cannot increase more than 11 percent per year
- As of 2026, Monroe County wind-only policyholders through Citizens saw an estimated 11 percent rate reduction compared to prior years
- Personal lines coverage limits go up to $1 million for wind-only policies
- Hurricane deductibles apply, typically 2 to 10 percent of the dwelling value depending on the policy
For properties in Key West, Marathon, and other incorporated Keys communities, both Citizens and private-market wind policies are available. The right choice depends on the property's location, age, construction type, and your individual risk tolerance.
What Does Wind Insurance Cost in the Florida Keys?
Wind insurance costs in the Florida Keys are the highest in the state, and Monroe County consistently ranks as Florida's most expensive county for homeowners insurance overall.
For 2026, here are the typical wind-only insurance ranges for Keys properties:
- Single-family homes: $4,000 to $12,000 per year, with many typical homes falling in the $7,000 to $10,000 range
- Waterfront and older homes: $12,000 to $22,000 per year
- Newer elevated construction with mitigation features: $3,500 to $7,000 per year
- Condominiums: Wind insurance for condo owners is typically covered by the HOA master policy, meaning individual unit owners pay for wind coverage through their monthly association dues rather than a separate policy
These are wind-only premiums. Combined with standard hazard insurance and flood insurance, total annual insurance costs for a typical Keys home often range from $15,000 to $25,000 or more. This is a significant factor in determining what you can afford, and it is why insurance costs belong in your homebuying budget from the very first conversation.
The 50 Percent Rule: What Keys Homeowners Need to Know
Monroe County enforces the 50 Percent Rule, which applies when a structure sustains damage equal to 50 percent or more of its pre-disaster fair market value. When that threshold is crossed, the structure must be brought into full compliance with current Florida Building Code requirements, including wind mitigation standards.
This rule has two practical effects for homeowners:
- After a major storm, older homes may face significantly higher rebuilding costs
- Older homes that have not been substantially renovated since the current building codes took effect may not be eligible for the best wind insurance rates
The 50 Percent Rule also affects property values. A home that is substantially non-conforming may be harder to insure and finance, especially for buyers using FHA loans or conventional financing that require insurable properties.
Wind Mitigation Credits: How to Save Thousands
Florida Statute Section 627.0629 requires insurers to offer premium discounts for properties with documented wind mitigation features. These credits can reduce your wind insurance premium by 20 to 40 percent, which in the Keys can mean $2,000 to $5,000 or more in annual savings.
A licensed wind mitigation inspector uses the OIR-B1-1802 form (revised as of April 1, 2026) to document specific features of the property. The features that qualify for the largest credits include:
- Impact-rated glazing: Impact-resistant windows, doors, and skylights that meet Miami-Dade County product approval standards
- Roof shape: Hip roofs receive larger credits than gable roofs because they are more aerodynamic in high winds
- Roof deck attachment: Stapled versus nailed roof sheathing and the spacing of fasteners
- Secondary water resistance: A self-adhering membrane under the roof covering that prevents water intrusion if the primary roof covering is damaged
- Roof-to-wall connections: Hurricane straps, clips, and tie-downs that secure the roof structure to the walls
- Opening protection: Hurricane shutters or impact-resistant glass covering all exterior openings
If you are buying a home in the Keys, ask the seller for the wind mitigation inspection report before you make an offer. If one does not exist, factor the cost of a wind mitigation inspection (typically $100 to $250) into your due diligence budget. An older home without impact windows or a modern roof deck may still qualify for meaningful credits after installing opening protection, and the improvements you make can reduce future premiums for the life of the policy.
How Wind Insurance Affects Your Mortgage
Wind insurance affects every mortgage in the Florida Keys, but its impact varies by loan program.
For conventional loans, the lender requires proof of wind coverage before closing. The annual premium is added to your total housing payment and factored into your debt-to-income ratio. If wind insurance costs $8,000 per year, that adds roughly $667 per month to your housing costs before principal, interest, taxes, or flood insurance.
For FHA loans, the same requirements apply: wind insurance must be in place from day one. FHA appraisers also check for general property condition, and an outdated roof or missing opening protection can become a condition issue.
For jumbo loans, which are common for high-value Keys waterfront properties, wind insurance requirements are often stricter. Jumbo lenders typically require higher coverage limits and may require documentation that the property meets specific wind mitigation standards.
For DSCR loans on investment properties, wind insurance is factored directly into the Debt Service Coverage Ratio calculation. Higher wind insurance means more rental income is needed to achieve the same DSCR, which can make some investment properties harder to finance.
For investment property and second home loans, the insurance picture is the same as for primary residences. All lenders require full coverage including wind, regardless of whether you live in the home year-round.
Wind Insurance for Condos in the Keys
If you are buying a condominium in the Florida Keys, wind insurance works differently than it does for single-family homes. The condo association's master policy typically covers wind damage to the building's structure and common areas. Individual unit owners are responsible only for the interior of their unit, and their wind exposure is generally covered through the HOA fees rather than a separate individual wind policy.
This is one reason why condos in the Keys can have lower total insurance costs than single-family homes. But there are important caveats. The HOA master policy's wind deductible and overall coverage adequacy matter because if the master policy has a large deductible or gaps in coverage, individual unit owners can face special assessments after a storm.
When financing a condo, your lender will review the HOA's master insurance policy to confirm that wind coverage is adequate. This is part of the condo project approval process for conventional, FHA, and VA loans. If the HOA's wind coverage is insufficient, the condo may not qualify for financing.
For Keys condos in buildings built before current wind codes were adopted, check whether the HOA has performed any wind mitigation improvements. Buildings with impact-resistant common-area windows and updated roof systems may qualify for lower master policy premiums, which keeps HOA fees more manageable.
What to Ask Before Buying a Keys Home
Before you make an offer on any Florida Keys property, here are the wind insurance questions you or your agent should ask:
- What is the current annual wind-only premium for this property?
- Is there an existing wind mitigation inspection report on file?
- What is the hurricane deductible? Is it 2 percent, 5 percent, or 10 percent of the dwelling value?
- Are the windows impact-rated or protected by hurricane shutters?
- What year was the roof installed, and what type of roof covering and deck attachment were used?
- Is the property insured through Citizens or a private carrier?
- If this is a condo, what does the master policy cover and what is the HOA's wind deductible?
Getting these answers during the due diligence period means no surprises at the closing table.
The Advocacy Picture: FIRM and Monroe County
Since 2006, a local advocacy group called Fair Insurance Rates in Monroe (FIRM) has worked to preserve affordable wind insurance for Keys residents. FIRM has saved Monroe County homeowners over $760 million through rate challenges and legislative advocacy. This is an important piece of the insurance landscape because it has helped keep Citizens wind premiums more stable than they might otherwise be.
Monroe County government also actively advocates for affordable wind insurance at the state level. Homeowners in the Keys benefit from more organized rate oversight than some other coastal Florida communities, though premiums remain among the highest in the state by any measure.
Budgeting for Wind Insurance as a Keys Buyer
Here is a practical framework for including wind insurance in your homebuying budget:
Step 1: Get a wind insurance quote for the specific property before you make an offer. Your real estate agent or insurance agent can request this.
Step 2: Add the annual wind premium to flood insurance and standard hazard insurance to get your total annual insurance cost.
Step 3: Divide by 12 for the monthly insurance cost and add it to principal, interest, and property taxes.
Step 4: Compare the total monthly payment to your lender's pre-approval amount. If insurance pushes the total payment too high, you may need to adjust your price range.
Step 5: If the property does not have impact windows or a wind mitigation report, factor both into your post-closing budget. The savings from mitigation can pay for the improvements over time.
A pre-approval from a lender who understands Keys insurance costs will include realistic estimates for wind, flood, and hazard insurance from the start. This prevents the unpleasant surprise of finding out at the closing table that your total payment is hundreds of dollars higher than expected.
Ready to get pre-approved and see how wind insurance fits your budget? Start your pre-approval or contact me to talk through your specific situation.
Frequently Asked Questions
Is wind insurance required by law in the Florida Keys?
How much does wind insurance cost for a home in the Florida Keys?
Can I get wind insurance through Citizens Property Insurance?
How can I reduce my wind insurance premium in the Keys?
Does wind insurance affect my mortgage pre-approval amount?
Ready to Find a Home You Can Afford in the Keys?
Wind insurance does not have to be a dealbreaker. With the right property, a wind mitigation inspection, and a mortgage professional who understands Keys coastal financing, you can budget accurately and buy with confidence.
I work with Keys buyers every day to structure financing that accounts for the full cost of Keys homeownership, including wind, flood, and hazard insurance. If you are considering a home in the Florida Keys, let us run the numbers together.
Written by Austin Edwards, NMLS #2639747, Ocean Blue Lending
Published August 5, 2026
Flood Insurance Guide · Homeowners Insurance Guide · Learning Center